

Refinancing Dealer Credit
Low interest rates are driving dealers back to their banks and finance companies to discuss refinancing floorplans, mortgages and lines of credit. Accounting expert offers advice for preparing your case and deciding between fixed and variable rates.
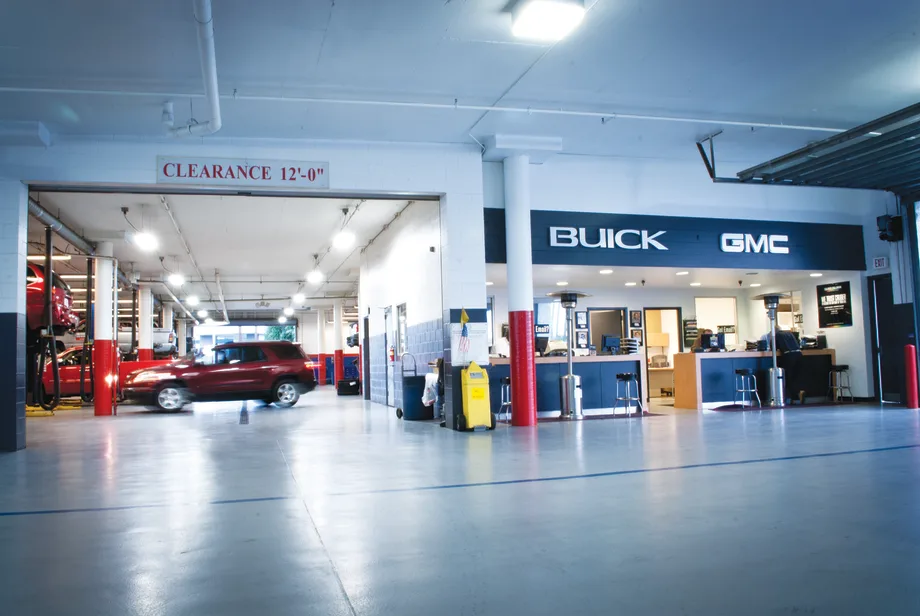
Facility upgrades and renovations are underway at dealerships across the nation. An improving economy and low interest rates have prompted many dealers to consider refinancing.
Over the past six to 12 months I have visited many dealers around the country and spoken to more by phone, and a hot topic has emerged: Dealers are talking about refinancing their floorplans, mortgages and lines of credit held by various banks and captive finance companies.
Why this sudden urge to refinance everything? Well, when the economy tanked a few years ago, most banks and captive finance companies put the brakes on any new loans or increases in existing loans. The few dealers who were in a position to grow their business were largely discouraged. Now, the economy is recovering — albeit very slowly — and banks want to loan money to dealers again. This is a good sign. Interest rates remain low and don’t appear to be moving anytime soon, and there is a lot money in the economy right now not earning a decent rate of return. Banks, investors and other financial institutions appear hungry to grow their own portfolios and increase their revenue.
Back in the Game
Happily, most financial institutions are not rushing back to market. They aren’t issuing loans or offering term sheets without first performing quite a bit of due diligence. They are being cautious and responding to new regulations and increased scrutiny from Washington. This is a good thing. Creditors will be more willing to lend money at reasonable rates if they know your business operations, net income and cash flow can justify the loan.
On dealership mortgages, it appears banks are somewhat more conservative than in the past. This shows up in real estate appraisals. Dealership real estate values are being tempered somewhat. This makes a difference in the total amount of money you can borrow; most banks limit the total to 80% of the appraised value.
This reduced valuation is also showing up among the many General Motors franchises in the midst of factory-mandated remodeling. Most dealers are borrowing the money to finance the remodeling, but in most cases, after the remodel is completed, their real estate value is only increasing by approximately 40-50% of the total cost of the construction.
Let’s say your store is appraised at $2 million, and you spend $800,000 to replace some of the existing facility and put up a new fascia out front. The appraiser returns and gives you a new value of $2.4 million. There is some logic to this: You are not going to get double credit for replacing, rather than adding, facilities. For this reason and others, it pays to shop around for the right financing package you need to suit your current operations and any future growth you may have planned.
Preparation Counts
It is important to have your act together and provide the correct information to your creditors in order to obtain the right financing. The cheapest rate today may not offer the best overall package for your future plans. The interest rate, whether fixed or variable; the term of the loan; collateral; personal or corporate guarantees; the required, CPA-issued financial statements; loan covenants on working capital ratios and cash flow; minimum debt service coverage ratios; and prepayment penalties are all very important items that must be addressed up front before any decision can be made.
Depending on how much of a risk-taker you are, you may elect to go with a variable rate. Yes, you run the risk of eventually paying higher rates during the next five years if interest rates start rising quickly. But most dealers I have talked to are willing to take the risk of utilizing the lower variable rates for their mortgages rather than lock themselves into a long-term deal. They are used to living with the floorplan rate being based on current prime rates with a “floor,” i.e., the minimum a bank will charge on a loan no matter how low interest rates fall. At the moment, interest rates don’t appear to be on the rise. Inflation is not out of control and the major economic indicators still fall on occasion.
Long-Term Planning
Most dealers operate on a month-to-month basis. They close out April, start May from scratch and then do it all over again in June. Naturally, as a result, most dealers tend to take a short-term view of their financing. Refinacing requires a wider perspective.
We typically like to see dealers finance their real estate for no longer than 15 years. After all, the factories introduce new facility standards about once every 10 to 15 years, and it’s nice to have the current facility paid off before you have to spend money again to spiff it up. Truth be told, planning for a facelift every 15 years would help some dealerships avoid the worn-out look that tends to creep up over time. That’s especially true for dealers who are not spending an adequate amount on repairs and maintenance each year.
If your dealership is close to being paid off, and you pledged multiple pieces of property or other assets for the loan at the beginning — or gave personal or corporate guarantees — you may want to talk to your financial institution. Ask whether they will release the unneeded collateral or guarantees to allow you to finance some of your growth plans. If they won’t, your only path may be to refinance the remaining loan balance and offer less but sufficient collateral for the new loan.
You may want to drag out the current loan documents you signed way back when and read them over. The terms might no longer fit your plans. Consider changes that will reduce your interest expense, reduce the collateral held by the banks or rid yourself of various covenants which no longer apply. Be careful to thoroughly read your documents before signing them and know what you are locking yourself into. Some loans carry fairly stiff prepayment penalties if you pay off the existing bank with refinancing provided by another financial institution.
Let me know how you do. Good luck!
David Keller is principal of CliftonLarsonAllen, an accounting firm with expertise in new- and used-car operations and heavy truck and utility trailer outlets. DKeller@AutoDealerMonthly.com
More Dealer Ops
How to Avoid Phone Scams | Dealer Debrief 09/10/2026
Are you taking the necessary steps to protect your dealership and customer data from phone-based scams? This week's Dealer Debrief breaks down how!
Read More →
Dealer Debrief: August Auto Sales
Gas-powered engines still dominate the U.S. vehicle market, but hybrids are gaining ground as consumers look for ways to cut their gas costs.
Read More →
Dealership Profits Decline
While new and used retail sales stagnated, dealerships have been particularly supported by fixed operations and finance-and-insurance profits, according to a new report.
Read More →
Dealer Debrief: Defection Data & EV Updates
In this week's debrief, host Lauren Lawrence discusses how to use defection data to your advantage and the latest on EV sales and charging infrastructure.
Read More →
How Defection Data is Bridging the Dealership Conversion Gap
Lead volume is flat, cross-shopping is up and brand loyalty is in retreat. As confident sales teams keep losing buyers they thought they had, daily industry sales data is showing dealers exactly where their funnel is breaking and how to fix it without buying a single new lead.
Read More →
Dealer Debrief: Where are you losing customers?
In this week's debrief, host Lauren Lawrence discusses the hidden leaks in dealerships where you might be losing customers without even realizing it.
Read More →
Dealer Debrief: Improving Your Inventory Management
In this week's debrief, host Lauren Lawrence covers a new survey that shows what service technicians really want and two launches that could help improve your inventory and vehicle life cycle management.
Read More →
Ladies and Gentlemen, This Is a Dealership: Why the Fundamentals Still Decide Who Wins
A teaching moment by a legendary football coach happens to apply perfectly in the auto retail space. Learn what it is and how to use it to your store’s advantage.
Read More →
Dealer Ads and the FTC
The agency has made it clear in recent enforcement actions and warnings, in auto retail and other industries, that advertised prices must include all nonoptional costs to the consumer.
Read More →
Used Autos Supply Dwindles
The March shopping surge, despite high prices, cut into inventory by the most since the thick of the pandemic, Cox Automotive analysts calculated.
Read More →